
For a helpful video guide on avoiding these errors, check out the accounting mistakes. Additionally, errors of commission can include reversed entries where debits and credits are swapped or duplicated entries. If the trial’s total debit and credit side do not https://azhandwerker.de/what-is-salvage-value-and-how-to-calculate-after/ agree in bookkeeping, some accounting error might occur, leading to disagreement. However, some errors do not affect the trial balance agreement yet may have been incurred. Thus it is important to understand the impact of accounting errors on Trial Balance. Apply accounting principles uniformly across all your financial reporting.
Preventing Duplicate Entries Automatically
- The rectification of errors is a critical process that ensures accuracy in financial records.
- Both debit which is accounts receivable and credit, sales revenue, has been recorded as $5,706.
- Posting the wrong amount in an account is known as the error of original entry.
- Reviewing your trial balance (via your accounting software) is one way to find different types of errors.
- You might have to pay extra hours for the work they put in reviewing and correcting these mistakes.
- Ensure employees understand key accounting principles and regulations to avoid errors like errors of principle or misclassification.
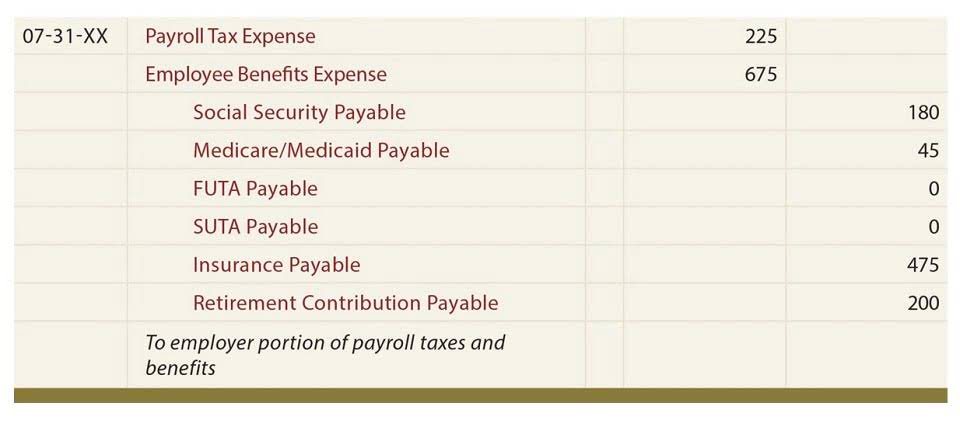
An example of a principle error is buying a piece of equipment and miscategorizing the expense as a sale instead of a purchase. This can throw your books out of balance, compromise the accuracy of your financial statements, and, if not caught, affect your tax liability. This guide maps out 10 common accounting errors, including the signs to look out for, how to prevent them, and what impact they can have on your business. This online accounting software allows you to easily calculate taxes (like VAT and sales tax), issue tax reports, and ensure compliance with local tax laws.
Error of Principle:
For businesses with physical inventory, a mismatch between the recorded inventory and the actual stock can indicate problems in bookkeeping. Failure to resolve this type of error in accounting before submitting your financial statement report can lead to costly repercussions. It’s because a compensating error happens when two entries offset each other, making the books appear balanced. Rounding a number off seems like it shouldn’t matter but it can throw gross vs net off your accounting, resulting in a snowball effect of errors.
- Where a transaction is not recorded in Journal or not at all posted in the respective ledger accounts.
- The primary objective of rectification is to maintain the accuracy of financial statements and ensure they reflect the true financial position of a business.
- Let us take care of your books and make this financial year a good one.
- Educate your finance team on accounting principles, common error types, and rectification procedures to improve awareness and competence.
- Making changes to financial data after the close date could result in future problems for reconciling your books and generating accurate financial statements.
Common Accounting Errors: Types of Accounting Errors And How To Avoid Them
Now, if you hold this receipt against another client’s bills, you’ve made a commission error. Even though this error seems small, writing an expense amount of “$3,678” instead of “$6,378” can throw off your entire finances. Make sure staff are kept updated types of errors in accounting with examples and are well-versed on proper account classification. Building out, and maintaining, a detailed chart of accounts is well worth doing. The words’ debit’ and ‘credit’ have originated from the Latin words ‘debitum’ and ‘creditum’. Ideally, this entry should have been reversed before the revised Vendor accrual for YTD March is calculated and posted.
Accounting Errors Which do not Affect the Trial Balance
Accounting errors may be defined as those mistakes which are generally committed while recording the financial transactions in the book of accounts. These errors may be committed while recording the transactions in the journal and posting them in the ledger accounts. Such errors may be technically committed or committed due to lack of the knowledge of accounting principles and rules. However, it may intentionally be committed so as to take some undue advantage.
- Accounting mistakes can manifest into severe financial and operational issues.
- Indeed, financial inaccuracies can damage the reputation of a small business, affecting relationships with suppliers, customers, and investors.
- These errors typically arise when transactions are recorded in the wrong account, leading to incorrect classification.
- The location of errors will be easier if the following steps are systematically taken.
- A good example of a potential error is a mismatch between the credits and debits on the trial balance.
